Thought Leadership
Entry Is Screened. Tenure Is Not. Mark O'Neill on Football's Real Regulatory Gap
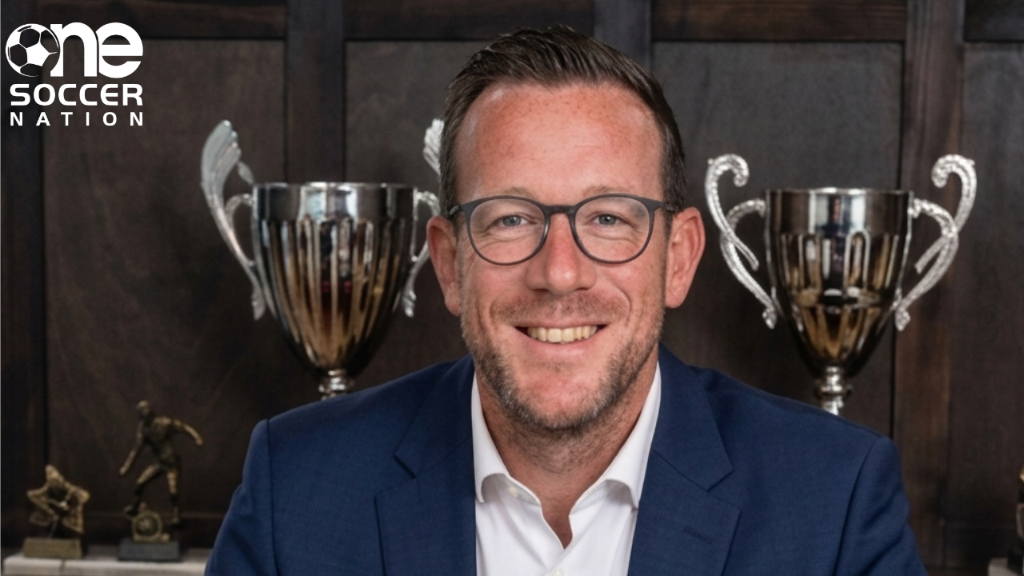
"You can't be both. You're lying to someone there."
That is Mark O'Neill on Saudi Arabia's Public Investment Fund, which assured the Premier League it was separate from the Saudi state, then argued sovereign immunity in a New York courtroom because it was part of the Saudi state. O'Neill is a PhD researcher at the University of Westminster studying whether football's ownership regulations actually protect anyone. He sits on FA disciplinary panels, and he supports Crystal Palace, which put him inside the most instructive governance case of the past year. On the One Soccer Nation Podcast, he walked through what the rulebook catches, what it misses, and who pays for the gap. Nine takeaways for anyone allocating capital into this asset class.
1. The owner test fires only after the trigger
England's owners and directors test screened Dai Yongge into Reading, then watched him disengage for years. O'Neill's account of the failure mode:
The test cleared him at entry, when he was funding one of the division's highest wage bills. The league's mid-tenure tools, points deductions and small fines, punished the club more than the owner. Disqualification only became possible once an unsatisfied court judgment in China supplied a formal trigger, with the club days from collapse.
The test screens entry. It does not police tenure.
2. Decline is gradual. Collapse is sudden.
O'Neill cites a period when the average Championship wage-to-revenue ratio ran around 107 percent, meaning the typical club spent more on players than it earned in total. That structure makes every club a derivative of its owner's willingness to fund. When funding stops, fire sales follow, results turn, attendance softens, and the revenue cycle goes vicious. As he puts it: "It may not necessarily happen quickly, but it does happen suddenly."
3. The new regulator closes the trigger gap, then grandfathers the risk
England's independent football regulator brings ongoing financial monitoring, business plan reviews, and powers to force out a failing owner. O'Neill credits the design, then flags the hole: existing owners are not subject to the mandatory reassessment new owners face. They get examined only if something surfaces. For a buyer entering a league, that means the least scrutinized counterparties are the incumbents.
The riskiest cohort is the least examined one.
4. Palace were punished for a conflict that had already been cured
The facts: John Textor's Eagle Football held a 43 percent stake in Palace while controlling Lyon, both qualified for the Europa League, and UEFA's rules assess conflicts as of March 1. Palace were only FA Cup quarterfinalists on that date. They won the Cup in May, Textor completed the sale of his stake to Woody Johnson, the former US ambassador to the United Kingdom, for a reported £190 million in July, and UEFA demoted Palace anyway. CAS upheld it. This is not a multi-club ownership story. It is an assessment-date formalism story, where a cured conflict was punished because the cure arrived after an arbitrary calendar line. Palace then won the Conference League outright in Leipzig last month, which softened the outcome without changing the precedent.
5. Blind trusts were the big-club exemption
The inconsistency is the signal. Manchester City's group conflict with Girona and Manchester United's Ineos conflict with Nice were resolved through blind trust arrangements and both played on. Palace, and smaller clubs like Ireland's Drogheda United, absorbed the enforcement. O'Neill on whether billionaires genuinely lose influence over shares parked in a blind trust: "I've got a bridge to sell you." He notes UEFA appears to be moving away from the mechanism, which, if it holds, removes the workaround the largest networks relied on.
Enforcement scaled with club size. That is the precedent capital should price.
6. The rules are fine. The application is not.
O'Neill's structural read on multi-club ownership, now spanning an estimated 400 clubs globally: the written rules adequately target the real risk, which is sporting integrity, but application has been inconsistent, and the vertical model extracts from the bottom of each network. Strasbourg fans watching their best players and their manager flow to Chelsea are the case study. His compromise proposal, since an outright ban is politically dead: one club per continental confederation per network.
7. Sovereign capital carries forced-sale risk
The Newcastle and Chelsea cases bracket the same lesson. The Premier League initially blocked PIF over state ties and a broadcast piracy dispute, then accepted separation assurances the LIV Golf litigation later contradicted. Abramovich was forced by the UK government to sell Chelsea within weeks of the Ukraine invasion, and the proceeds still sit frozen while parties argue over distribution. For an LP, the underwriting question is not whether sovereign-adjacent capital is ethical. It is whether a political event can mandate divestment on a timeline you do not control, at a price you do not set.
8. The entry arbitrage still runs through Europe's lower tiers
Promotion converts operating spend into enterprise value, which is why O'Neill points to Wrexham, bought for roughly £2.5 million and now carrying analyst valuations he cites around £400 million, as the reference trade. He flags Serie B and C, Belgium, and Portugal as undercapitalized markets with favorable player-registration rules, with Germany largely closed by 50+1. Celebrity equity is part of the same playbook: KSI's 20 percent stake in sixth-tier Dagenham & Redbridge is distribution strategy, not vanity, attaching a 17-million-subscriber audience to a non-league cap table.
9. Extraction is rising faster than the product
O'Neill applies the enshittification framework to football: committed fans locked in, then squeezed. His evidence set: a £4 Liverpool ticket in 1990 that inflation says should cost about £9.60 and instead costs £39, a match calendar so saturated that stars rotate out, and clubs chasing the higher-spending casual visitor over the season-ticket core. The risk for owners is that the core fan is the product. Degrade the atmosphere and the broadcast asset degrades with it.
Final Word
O'Neill's unpublished stage-one survey data, shared on the show for the first time, says fans reward owners with sporting ambition, transparency, and respect for tradition, and that fandom is less fixed than assumed: only around 54 percent support their local club, and roughly 22 percent have switched clubs in their lifetime. His one-sentence advice to a first-time buyer, after a deadpan "run," is the cheapest diligence available: "Listen to the fans, as they will tell you more about a club than any consultant or lawyer or accountant will."
Listen to the full episode
Comments
No comments yet. Be the first to share your thoughts.